Why Some of Southeast Asia’s Digital Banks are Starting to Scale
Por James Guild — The Diplomat
Read The Diplomat , Know The Asia-Pacific
Can these institutions threaten the entrenched conventional mega-banks that dominate the region’s financial landscape?
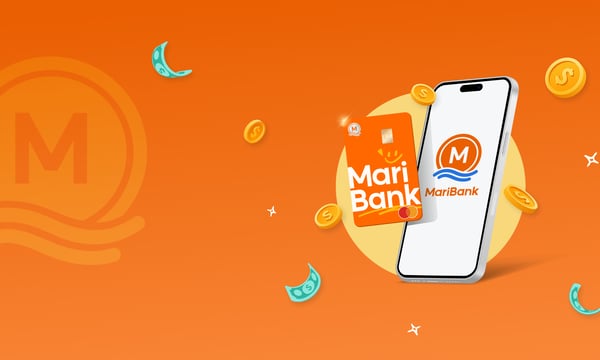
An online advertisement for MariBank, a digital bank based in Singapore.
The world of digital banking is an odd place. A digital bank offers the same basic services as a traditional bank – takes deposits, makes loans – but it does it almost entirely online, eliminating much of the overhead required to maintain a network of brick and mortar branches. Digital banks in this context are standalone businesses, as opposed to digital offshoots of existing banks like Jenius in Indonesia or Trust Bank in Singapore. In fact, if the business model can scale, digital banks might pose a serious threat to the entrenched position of conventional mega-banks that dominate Southeast Asia’s financial landscape.
Despite the promise, digital banking has developed unevenly across Southeast Asia. In Vietnam, there are no true digital banks as digital finance platforms must partner with or be a subsidiary of an existing commercial bank. Regulators in Thailand have also moved slowly in getting the first few digital banks up and running and big potential players, like CP Group’s Ascend Bank, have encountered delays. Indonesia sits on the other end of the spectrum, with digital banks backed by major tech and telecom firms seeing take-off, adding billions in customer deposits and rapidly scaling their loan portfolios over the last few years.
Indonesia’s experience provides some clues about when, why and how digital banks can scale. A key consideration is the regulatory environment. A regulatory system that is supportive of digital banks can open the door for new entrants to challenge incumbents and introduce potentially disruptive innovation into existing systems of banking and finance. Indonesian regulators showed an early willingness to allow this, which is not that surprising given there was a larger tech sector boom underway at the time. That boom has deflated somewhat now, although digital banks remain one of the more promising and profitable legacies of the boom.
In countries with more mature banking sectors, like Singapore, regulators have been cautious in growing digital banks, despite approving the first round of full licenses several years ago. MariBank, owned by tech conglomerate Sea, launched in 2022. Because MariBank is integrated into the Sea ecosystem, which includes its enormous e-commerce arm Shopee, it had amassed S$1.9 billion in deposits by 2025. But limited by tight regulatory oversight, MariBank made only S$222 million in loans and posted a S$56 million loss.
GSX bank, a partnership between telecom giant Singtel and online ride-hailing company Grab, tells a similar story with S$1.8 billion in deposits against S$777 million in loans, and a net loss in 2025. In both cases, the majority of their assets are parked with the central bank or in government and corporate bonds. GSX’s Malaysian arm, GX Bank Berhad, has also been slow out of the gate, reporting total assets of $479 million as of 2025 and a loan to deposit ratio of just 25 percent. There are signs, however, that activity may finally be picking up, with loans jumping 76 percent between December 2025 and June 2026.
In addition to permissive regulatory conditions, the scalability of digital banks depends to a large extent on who is backing them and how digital banking services can be integrated into wider existing commercial ecosystems. In particular, companies that have existing customer networks and use big digital platforms, like telecom and e-commerce companies, have an advantage.
In the Philippines, digital banking appears to be down to a two-horse race between Sea (a familiar refrain by now) and local telecom major PLDT. By the end of 2025, Sea’s MariBank Philippines had assets of just over $1 billion, with its loan portfolio growing 64 percent year over year. Maya Bank, in which PLDT is the main shareholder, reported $1.25 billion in assets and saw its loan book jump 86 percent compared to 2024.
This aligns with what we are seeing in Indonesia, where a friendly regulatory environment combined with backing from major tech, telecom and institutional investors has been decisive in determining which digital banks are scaling and which are stagnating. A very similar story is playing out in the Philippines, while in other countries, even if the institutional backing is there, the regulatory environment may be moving more slowly. For the time being, that’s what is holding back the kind of explosive growth one might have expected when regulators first started issuing digital banking licenses several years ago.
Subscribe today and join thousands of diplomats, analysts, policy professionals and business readers who rely on The Diplomat for expert Asia-Pacific coverage.
Get unlimited access to in-depth analysis you won’t find anywhere else, from South China Sea tensions to ASEAN diplomacy to India-Pakistan relations. More than 5,000 articles a year.
Already have an account? Log in .
The world of digital banking is an odd place. A digital bank offers the same basic services as a traditional bank – takes deposits, makes loans – but it does it almost entirely online, eliminating much of the overhead required to maintain a network of brick and mortar branches. Digital banks in this context are standalone businesses, as opposed to digital offshoots of existing banks like Jenius in Indonesia or Trust Bank in Singapore. In fact, if the business model can scale, digital banks might pose a serious threat to the entrenched position of conventional mega-banks that dominate Southeast Asia’s financial landscape.
Despite the promise, digital banking has developed unevenly across Southeast Asia. In Vietnam, there are no true digital banks as digital finance platforms must partner with or be a subsidiary of an existing commercial bank. Regulators in Thailand have also moved slowly in getting the first few digital banks up and running and big potential players, like CP Group’s Ascend Bank, have encountered delays. Indonesia sits on the other end of the spectrum, with digital banks backed by major tech and telecom firms seeing take-off, adding billions in customer deposits and rapidly scaling their loan portfolios over the last few years.
Indonesia’s experience provides some clues about when, why and how digital banks can scale. A key consideration is the regulatory environment. A regulatory system that is supportive of digital banks can open the door for new entrants to challenge incumbents and introduce potentially disruptive innovation into existing systems of banking and finance. Indonesian regulators showed an early willingness to allow this, which is not that surprising given there was a larger tech sector boom underway at the time. That boom has deflated somewhat now, although digital banks remain one of the more promising and profitable legacies of the boom.
In countries with more mature banking sectors, like Singapore, regulators have been cautious in growing digital banks, despite approving the first round of full licenses several years ago. MariBank, owned by tech conglomerate Sea, launched in 2022. Because MariBank is integrated into the Sea ecosystem, which includes its enormous e-commerce arm Shopee, it had amassed S$1.9 billion in deposits by 2025. But limited by tight regulatory oversight, MariBank made only S$222 million in loans and posted a S$56 million loss.
GSX bank, a partnership between telecom giant Singtel and online ride-hailing company Grab, tells a similar story with S$1.8 billion in deposits against S$777 million in loans, and a net loss in 2025. In both cases, the majority of their assets are parked with the central bank or in government and corporate bonds. GSX’s Malaysian arm, GX Bank Berhad, has also been slow out of the gate, reporting total assets of $479 million as of 2025 and a loan to deposit ratio of just 25 percent. There are signs, however, that activity may finally be picking up, with loans jumping 76 percent between December 2025 and June 2026.
In addition to permissive regulatory conditions, the scalability of digital banks depends to a large extent on who is backing them and how digital banking services can be integrated into wider existing commercial ecosystems. In particular, companies that have existing customer networks and use big digital platforms, like telecom and e-commerce companies, have an advantage.
In the Philippines, digital banking appears to be down to a two-horse race between Sea (a familiar refrain by now) and local telecom major PLDT. By the end of 2025, Sea’s MariBank Philippines had assets of just over $1 billion, with its loan portfolio growing 64 percent year over year. Maya Bank, in which PLDT is the main shareholder, reported $1.25 billion in assets and saw its loan book jump 86 percent compared to 2024.
This aligns with what we are seeing in Indonesia, where a friendly regulatory environment combined with backing from major tech, telecom and institutional investors has been decisive in determining which digital banks are scaling and which are stagnating. A very similar story is playing out in the Philippines, while in other countries, even if the institutional backing is there, the regulatory environment may be moving more slowly. For the time being, that’s what is holding back the kind of explosive growth one might have expected when regulators first started issuing digital banking licenses several years ago.
James Guild is an expert in trade, finance, and economic development in Southeast Asia.
Get briefed on the story of the week, and developing stories to watch across the Asia-Pacific.
Fonte: The Diplomat